- Nerd Out on Business
- Posts
- Their Smart Pricing Pivot Masks an Overhead & Debt Problem
Their Smart Pricing Pivot Masks an Overhead & Debt Problem
Marti’s driver subscription model flipped its margins, proving that sometimes the best way to monetize a marketplace is to charge the suppliers, not the customers.

Nick Horob
October 30, 2025
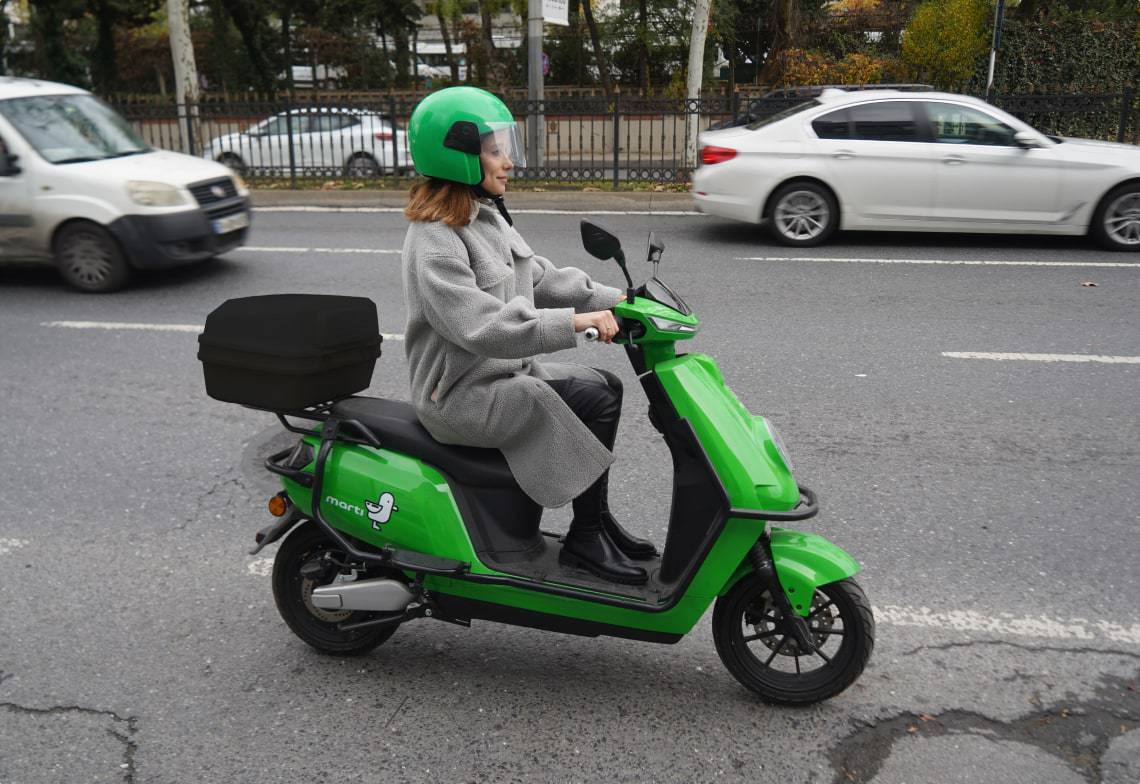
Today, I’m digging into Marti Technologies (MRT). They are a mobility "super-app" trying to be Turkey's answer to both Uber and Bird/Lime.
Marti started with scooters, then added cars, taxis, and mopeds all in one app. It’s now monetizing its ride-hailing side by charging drivers a subscription fee instead of taking a per-ride cut.
There's one part of this pricing change that really confused me: the research I came across touted their move to dynamic pricing as really helping drive margins. But if you're not taking a cut of each ride, how would you benefit from dynamic pricing?
This shift gives drivers predictable earnings and lets Marti earn steady recurring revenue while using dynamic pricing to boost driver demand, ride volume, and perceived subscription value.
That change helped flip its gross margin from negative to +22%, but the rest of the story isn’t all smooth riding.
Here’s what stood out:
Business model pivot: Marti moved from free ride-hailing to driver subscriptions and dynamic pricing. That fixed the unit economics fast.
Revenue comeback: TTM sales are up to about $24.6M, and 1H25 revenue jumped 70% YoY.
Positive gross margin: Finally in the black on gross profit after years of negative margins.
Debt/overhead overhang: But net debt sits around $79M, and operating losses are still massive at roughly -243% margin.
Single-country risk: Marti operates entirely in Turkey. Geographic focus is a must when it comes to building up both sides of a double-sided marketplace, but it has limited diversification if regulators tighten up again.
Takeaway:
I actually quite like the business model of the company. But like so many tech start-ups, they take on way too much overhead. I can't help but think a lot of these companies would still be successful with 20-40% of their overhead.
Their pricing and business model changes are impressive, but you can't rely on gross margin improvements alone to right the ship of a company that's losing so much money.
With that, I'll see you tomorrow!
Nick
TL;DR
Marti runs a dual business: ride-hailing and micromobility (e-scooters, e-bikes, e-mopeds) through one app in Turkey.
It pivoted from free ride-hailing to driver subscriptions in Oct 2024, then added dynamic pricing in Jan 2025.
TTM revenue grew while gross margins turned positive for the first time.
Still, heavy debt and ongoing operating losses mean profitability is far off.
Entrepreneur takeaway: pricing pivots can fix margins, but cash structure can make or break your turnaround.
The 30,000-Foot View
Business model
Two lines under one app:
Ride-hailing monetized through driver subscription packages.
Micromobility rentals priced per unlock and per minute.
Focus shifted toward monetizing ride-hailing starting in late 2024.
Main revenue sources
Ride-hailing driver subscriptions and vehicle rentals.
No official % mix disclosed, but ride-hailing’s share grew sharply after Oct 2024.
Key stats
Market cap: ~$184M
TTM revenue: $24.6M
TTM gross margin: 22.6%
TTM adjusted EBITDA: -$13.9M
Employees: ~440
Industry: Application Software (Technology)
Marti is a hybrid between Uber and Lime, combining asset-heavy operations (in their micromobility segment) with a marketplace model.
Company History
2018: Founded in Turkey; first micromobility launches in 2019.
Oct 2022: Launches ride-hailing (car and motorcycle).
Jul 2023: Goes public via SPAC merger with Galata Acquisition Corp, trading as MRT.
Feb 2024: Adds taxi-hailing.
Oct 2024: Begins monetizing ride-hailing via driver subscriptions.
Jan 2025: Launches dynamic pricing for ride-hailing.
1H 2025: Revenue rises 70% YoY to $14.3M as monetization gains traction.
Sep 2025: Files 6-K showing improved gross margin but continued losses.
Show Me the Money
Stand-Out Financial Features
Gross margin turnaround: From negative to +22.6% TTM after monetizing ride-hailing.
Operating losses remain extreme: -243% TTM operating margin.
Rising leverage: Net debt up to ~$79M, mostly high-interest convertible notes.
Capex restraint: Cut from $8M+ to <$1M as fleet growth paused.
Revenue momentum: +70% YoY in 1H25, though not yet profitable.
Summary: The business finally found a path to positive unit economics but hasn’t proven sustainable cash flow yet.
Financial Data
Metric | 2022 | 2023 | 2024 | TTM |
|---|---|---|---|---|
Revenue | $25.0M | $20.0M | $18.7M | $24.6M |
Gross Profit | -$2.1M | -$4.1M | -$2.9M | $5.5M |
Gross Margin | -8.4% | -20.2% | -15.5% | 22.6% |
Ops Profit | -$14.9M | -$30.6M | -$65.3M | -$59.6M |
Ops Margin | -59.6% | -152.8% | -350.0% | -242.6% |
CapEx | $8.0M | $4.7M | $0.3M | $0.5M |
Net Debt | n/a | $45.8M | $69.5M | $78.8M |
The N.O.O.B. Nine — Competitive Powers
The Nerd Out on Business Nine is made up of Hamliton Helmer's famous "7 Powers" of competitive advantage (Scale Economies, Network Economies, Counter-Positioning, Switching Costs, Branding, Cornered Resource, and Process Power) combined with two of my own (Data Flywheel and Distribution Advantage).
Power | Score | Rationale |
|---|---|---|
Branding | 3/5 | Leading urban mobility app in Turkey, but regional scope limits global recognition. |
Data Flywheel | 3/5 | Rich trip and demand data support pricing and ops optimization. |
Process Power | 3/5 | Strong IoT integration and fleet ops, though replicable over time. |
Scale Economies | 3/5 | Costs drop with density and fleet utilization, but capex and maintenance limit scalability. |
Switching Costs | 2/5 | Users and drivers can move freely across apps; subscription offers short-term lock-in only. |
Cornered Resource | 2/5 | No exclusive licenses or tech moat; fleet ownership is replaceable. |
Network Economies | 3/5 | Classic two-sided marketplace effects, but loyalty is weak and multi-homing common. |
Counter-Positioning | 2/5 | Subscription model is different from Uber’s take rate, yet easy to imitate. |
Distribution Advantage | 3/5 | One app markets multiple services, but dependence on app stores adds risk. |
Average Score: 2.7/5 - Moderate local advantages, but limited moat beyond operational execution.
Memorable Marketing
Positioning Marti brands itself as “Turkey’s mobility app” and relies on in-app growth rather than heavy external marketing. Social, referral, and performance ads support the funnel.
Key Campaigns & Tactics
1. Ride-Hailing Monetization Launch (2024)
Hook: Turning free driver access into paid subscriptions.
Channels: In-app paywall, email/CRM.
Why it worked: Immediate recurring revenue from drivers, predictable cash flow.
Result: Helped fuel 70% YoY revenue growth in 1H25.
2. Dynamic Pricing Rollout (2025)
Hook: Real-time pricing based on rider demand and driver supply.
Channels: In-app algorithm and push notifications.
Why it worked: Improved balance and fairness, increasing active users.
Result: Conversion rate up ~2%, DAUs up ~16% YoY in 1H25.
3. Modal Cross-Sell Program (2024)
Hook: Encouraging users to try multiple modes (scooter, car, taxi).
Channels: App prompts and discounts.
Why it worked: Boosted retention and lifetime value while lowering CAC.
Tactical Takeaways for Founders
Price as marketing. Test revenue models like subscriptions before pouring money into ads.
Turn your app into the ad. In-product prompts outperform external traffic.
Measure like a scientist. Track conversion, cross-usage, and pricing experiments tightly.
Localize launches. Optimize one city before scaling the playbook.
AI Uses & Opportunities
Already in use
Dynamic pricing and fleet optimization for ride-hailing and micromobility.
Predictive maintenance to minimize downtime.
Real-time routing for support and battery-swapping teams.
Future opportunities
Driver churn prediction and price elasticity modeling by geography.
Smart battery routing for swap vans using energy and demand forecasts.
Fraud and safety scoring with behavioral data.
AI chat and support bots to raise ratings without more staff.
City-level forecasting for demand to inform local marketing spend.
Bumps in the Road
Legal & Regulatory
Ongoing lawsuits in Istanbul over ride-hailing legality; 2024 ruling unfavorable before appeal.
Taxi unions and regulators present constant friction.
Financial
Significant going-concern warnings due to operating losses and heavy debt.
Relies on convertible notes with a 12.5% interest rate due 2029.
Hyperinflation accounting adds reporting complexity for Turkish operations.
Operational
Single-country focus increases political and economic risk.
Capex-light strategy protects cash but risks underinvestment in fleet quality.
Your Swipe File
Monetize the supply side. When a take-rate model is tough, charge the suppliers (like Marti’s driver subscriptions).
Stop expanding until unit economics work. Shrinking fleet capex saved Marti.
Localize your business. Treat each city or region as its own P&L.
Debt ≠ growth. High-interest financing only delays profitability problems.
Expect regulatory pushback. Disruption invites lawsuits—prepare early.