- Nerd Out on Business
- Posts
- Incumbency Pays Dividends (literally) in Defense Electronics
Incumbency Pays Dividends (literally) in Defense Electronics
Leonardo DRS makes the kind of gear you’ll never see, but militaries can’t function without. Once their tech is qualified into submarines or vehicle platforms, it’s nearly impossible to swap them out. Incumbency their real moat.

Nick Horob
September 15, 2025
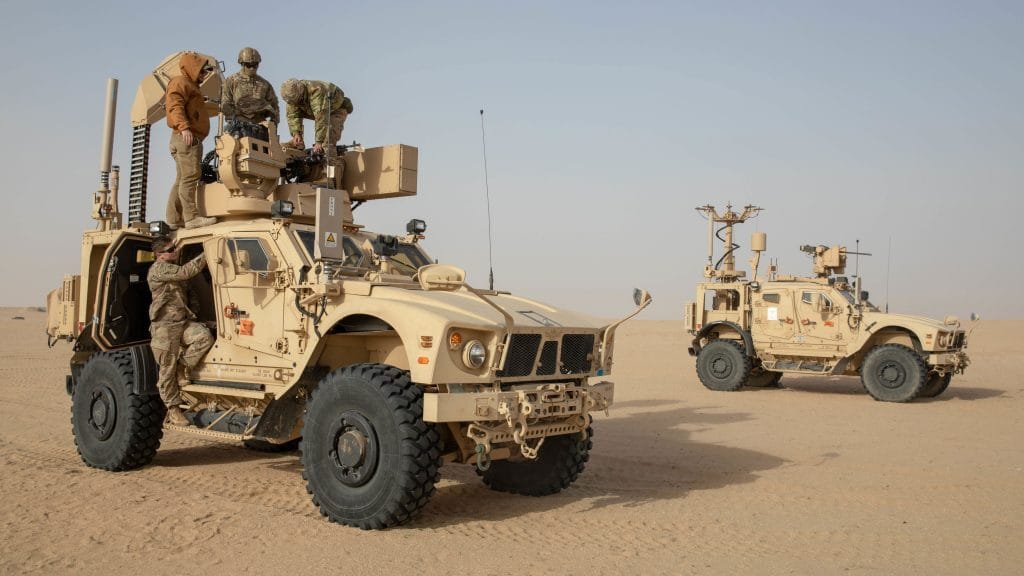
Today, I'm looking at Leonardo DRS (DRS). They are a mid-tier defense electronics supplier whose gear is used in U.S. military vehicles, submarines, and power systems.
A couple of highlights:
~$3.4B in TTM revenue with ~23% gross margins.
Backlog of ~$8.6B, giving them a few years of visibility locked in.
Programs like the Columbia-class submarine are sticky once you’re qualified as it’s nearly impossible to swap vendors midstream.
But it’s not all smooth sailing:
They’re heavily exposed to raw material costs (germanium price swings hurt margins in 2025).
The business lives and dies by U.S. defense budgets. This is the definition of concentration risk.
There is a near 100% chance that I wouldn't get involved in a business with these kind of products and their complexity, regulation, and government customer base.
With that said, I try to take something away from all of these reports, and the main takeaway here is that I was surprised to see how low their gross margins are given their complex products. This is a clear case of trading margins for the security of long-term government contracts. Not for me, but it makes sense.
I'll see you tomorrow....with a business that I'd be more likely to get involved in!
Nick
TL;DR
Leonardo DRS builds mission-critical defense electronics, spanning sensors, rugged computing, naval electric power, and force protection systems.
The company's edge is in winning and sustaining long-cycle programs such as the Columbia-class submarine, where qualification and incumbency create switching costs and repeat orders.
For entrepreneurs, the lesson is clear: focus on defensible niches, embed yourself deeply in customer workflows, and then scale with disciplined program execution rather than chasing hype.
While it lacks network effects, its real moat is reliability and program stickiness—traits that founders in B2B and industrial sectors can emulate.
The 30,000-Foot View
What it does and business model: Leonardo DRS is a mid-tier U.S. defense contractor specializing in advanced sensing and network computing for vehicles, ships, and integrated missions. It operates as a supplier to the Department of Defense and large primes like Lockheed Martin and Northrop Grumman. Revenue largely comes from multi-year government contracts, often fixed-price, which reward tight execution and cost control.
Revenue mix (2024):
Advanced Sensing and Computing: ~65%
Integrated Mission Systems: ~35%
Contract type: ~84% fixed-price (based on some sources, there may be some flexibility built-in to some of these fixed price contracts)
Revenue type: ~94% product vs services
Prime vs subcontract: ~37% prime, ~63% subcontract
Key stats:
Market cap: ~$11.2B
TTM revenue: ~$3.42B
Gross margin: ~23%
TTM Net income: ~$250M
Employees: ~7,000
Industry: Aerospace & Defense Electronics
Translation for entrepreneurs: this is a hardware-plus-integration business. The moat is not in marketing, but in qualification, relationships, and delivery in environments where mistakes are not tolerated.
Company History
1968–1981: Founded as Diagnostic Retrieval Systems, later known as DRS Technologies, eventually going public.
2008: Acquired by Finmeccanica (later Leonardo S.p.A.), anchoring it in an Italian defense conglomerate.
2022: Portfolio restructuring—sold Global Enterprise Solutions to SES for $450M and divested 51% of Advanced Acoustic Concepts to Thales.
Nov 2022: Completed an all-stock merger with Israel’s RADA, becoming a publicly traded company under ticker DRS.
2024: Reported record orders, building backlog to ~$8.5B.
2025: Initiated dividends and share buybacks
Show Me the Money
Stand-out features:
Backlog of ~$8.6B offers 2–3 years of revenue visibility.
Heavy product mix (94%) gives leverage to production efficiency.
High proportion of firm-fixed-price contracts means execution discipline is a profit driver.
Margins improved in 2024–2025 as Columbia-class programs moved into production.
Net cash in 2024 turned into modest net debt by mid-2025, funding dividends and buybacks.
Financial Data
Metric | 2022 | 2023 | 2024 | TTM |
|---|---|---|---|---|
Revenue | $2,693M | $2,826M | $3,234M | $3,421M |
Gross Profit | $575M | $648M | $736M | $792M |
Gross Margin | 21.4% | 22.9% | 22.8% | 23.2% |
Ops Profit | $561M | $231M | $293M | $324M |
Ops Margin | 20.8% | 8.2% | 9.1% | 9.5% |
CapEx | $65M | $60M | $85M | ~$101M |
Net Debt | ~$90M | ~-$60M | ~-$232M | ~$75M |
The N.O.O.B. Nine — Competitive Powers
The Nerd Out on Business Nine is made up of Hamliton Helmer's famous "7 Powers" of competitive advantage (Scale Economies, Network Economies, Counter-Positioning, Switching Costs, Branding, Cornered Resource, and Process Power) combined with two of my own (Data Flywheel and Distribution Advantage).
Power | Score | Rationale |
|---|---|---|
Branding | 3/5 | Strong B2G brand reputation, though irrelevant to consumers. |
Data Flywheel | 2/5 | Collects sensor data, but most insights belong to the customer, not DRS. |
Process Power | 4/5 | Strong program management and execution discipline drive consistent profitability. |
Scale Economies | 3/5 | Gains some advantage in procurement and facilities, but dwarfed by prime contractors. |
Switching Costs | 4/5 | Once embedded in submarines or vehicles, replacing DRS would require years of requalification. |
Cornered Resource | 4/5 | Proprietary IP in infrared sensing and cleared facilities gives it unique advantages. |
Network Economies | 1/5 | Defense subsystems don’t gain strength from more users—success is based on performance. |
Counter-Positioning | 2/5 | Carved out niches in sensors and naval systems, but not disruptive against incumbents. |
Distribution Advantage | 4/5 | Deep relationships with DoD and primes, plus incumbency on key programs. |
Average Score: 3/5 - This is a classic “moat by incumbency.” Not flashy, but hard to unseat once entrenched.
Memorable Marketing
Approach: Credibility-first. Focuses on trade press, defense shows, and technical storytelling. The message: “Our Agility, Your Advantage.”
Notable campaigns/tactics:
AI Processor Launch (2025)
Hook: On-edge AI for real-time threat detection.
Channels: press release, trade media demos.
Why it worked: Direct tie to mission outcomes.
Result: Positioned DRS as a tactical AI compute supplier.
AI-enabled Rugged Smart Displays (2025)
Hook: Upgrade path for Army vehicles to AI-capable displays.
Channels: press, program briefings.
Why it worked: Simple narrative, drop-in upgrade.
Result: Expanded installed base.
EO/IR Thought Leadership (2023)
Hook: AI improves detection and range.
Channels: defense trade articles.
Why it worked: Educated buyers, created pull.
Result: Boosted competitive positioning during RFPs.
Tactical Takeaways:
Simplify tech stories into mission outcomes.
Launch around existing standards to ease adoption.
Use thought leadership to make buyers smarter.
Announce R&D early to boost credibility.
AI Uses & Opportunities
Current uses:
AI-on-edge processors for tactical vehicles.
AI-enabled smart displays tied to Army standards.
Electro-optical sensors with machine learning.
Company-wide AI/ML Center of Excellence.
Future opportunities:
Predictive maintenance for naval power systems.
Bidding intelligence tools to improve pricing accuracy.
Sensor fusion kits with pre-trained AI models.
Supply chain AI to mitigate volatility in materials like germanium.
Bumps in the Road
Germanium price spikes in 2025 cut into sensor margins.
Program delays on a foreign surveillance project highlight risk in long-cycle work.
Budget exposure: U.S. appropriations cycles always loom as risk.
Customer concentration: Reliance on U.S. government contracts limits diversification.
Your Swipe File
Once you qualify in a niche, compound incumbency into a moat like DRS does with submarines and vehicles.
Productize around existing standards, then upsell with intelligence layers.
Watch your contract mix: fixed-price contracts mean margin lives and dies with execution.